Hyundai now covers compact city cars, family SUVs, hybrids and a broad electric range. Hyundai car finance can spread the cost of models such as the i10, Tucson, Santa Fe, Kona and IONIQ 5 while giving you different routes depending on mileage, deposit and how long you expect to keep the car.
Enjoy Finance explains the main funding options and links to third-party providers. We do not provide finance directly, and the website contains affiliate links.
How does Hyundai car finance work?
Hyundai Finance is a trading name of Hyundai Capital UK Limited. Its main personal products include Personal Contract Purchase, Personal Motor Loan and Personal Contract Hire.
PCP leaves part of the vehicle cost until the end, Personal Motor Loan repays the car through fixed monthly payments, and Contract Hire is based on using the car for an agreed period before returning it.
PCP gives you flexibility at the end
Hyundai PCP starts with a deposit, although Hyundai Finance states that you can choose not to put one down. You then agree the term and expected annual mileage.
Part of the vehicle cost is deferred until the end as an Optional Final Payment. That amount is calculated at the start using factors including the agreement duration and mileage allowance.
At the end, you can retain the vehicle by paying the final amount, return it subject to mileage and condition terms, or renew by part-exchanging it. Any equity above the final payment can potentially go towards another car, but Hyundai makes clear that equity is not guaranteed.
Read Personal Contract Purchase for a wider explanation of this type of agreement.
Current offers can differ sharply by powertrain
Hyundai regularly changes its manufacturer-backed finance offers rather than applying one APR across the range.
Current promotions include 0% APR on selected models, while others use lower promotional rates with deposit contributions. Some 0% offers are available over a maximum 36 months and can require a minimum deposit, while other campaigns have different terms.
That makes Hyundai car finance worth comparing model by model. Look at the customer deposit, Hyundai contribution, APR, monthly payments, Optional Final Payment and total amount payable together.
A 0% offer can look attractive, but a separate deal with a manufacturer contribution may reduce the amount being funded more effectively for a particular buyer.
Hyundai’s five-year warranty changes the ownership calculation
Every new Hyundai currently comes with a five-year unlimited-mileage manufacturer warranty.
That can be useful for drivers taking out a four or five-year agreement because the standard vehicle warranty can remain in place across the whole finance term, subject to the warranty conditions and servicing requirements.
Hyundai also provides an eight-year or 100,000-mile warranty on high-voltage batteries, whichever comes first.
This makes warranty length a genuine part of the Hyundai car finance comparison, particularly for drivers planning to keep an electric or hybrid model beyond the initial agreement.
Electric models bring different incentives and risks
Hyundai’s electric range includes the IONIQ 5, IONIQ 6, IONIQ 9, Kona Electric and INSTER, alongside newer electric models entering the range.
Electric-car values can move quickly as battery technology, pricing and incentives change. PCP can appeal to some buyers because the Optional Final Payment is agreed at the start, giving them the choice to return the car at the end subject to the agreement conditions.
Drivers considering the Hyundai Ioniq 5 Car Finance page should also compare charging access, annual mileage and battery warranty alongside the finance.
The Hyundai Kona Car Finance page is useful for buyers comparing petrol, hybrid and electric versions of the same model family.
Personal Motor Loan suits a different type of buyer
Hyundai uses Personal Motor Loan rather than calling its ownership-focused product Hire Purchase.
PML uses fixed monthly payments with no Optional Final Payment and no agreed annual mileage limit. Once all required payments have been made, the vehicle is yours.
Hyundai Finance currently allows PML terms between 12 and 60 months, subject to the vehicle and campaign.
This can suit someone who covers high mileage, wants to keep the same Hyundai for several years or does not want a large final payment. Buyers comparing ownership routes can also read Car Loans.
Tucson and Santa Fe buyers have different priorities
A family SUV buyer may care more about space, fuel use and annual mileage than someone choosing a smaller Hyundai.
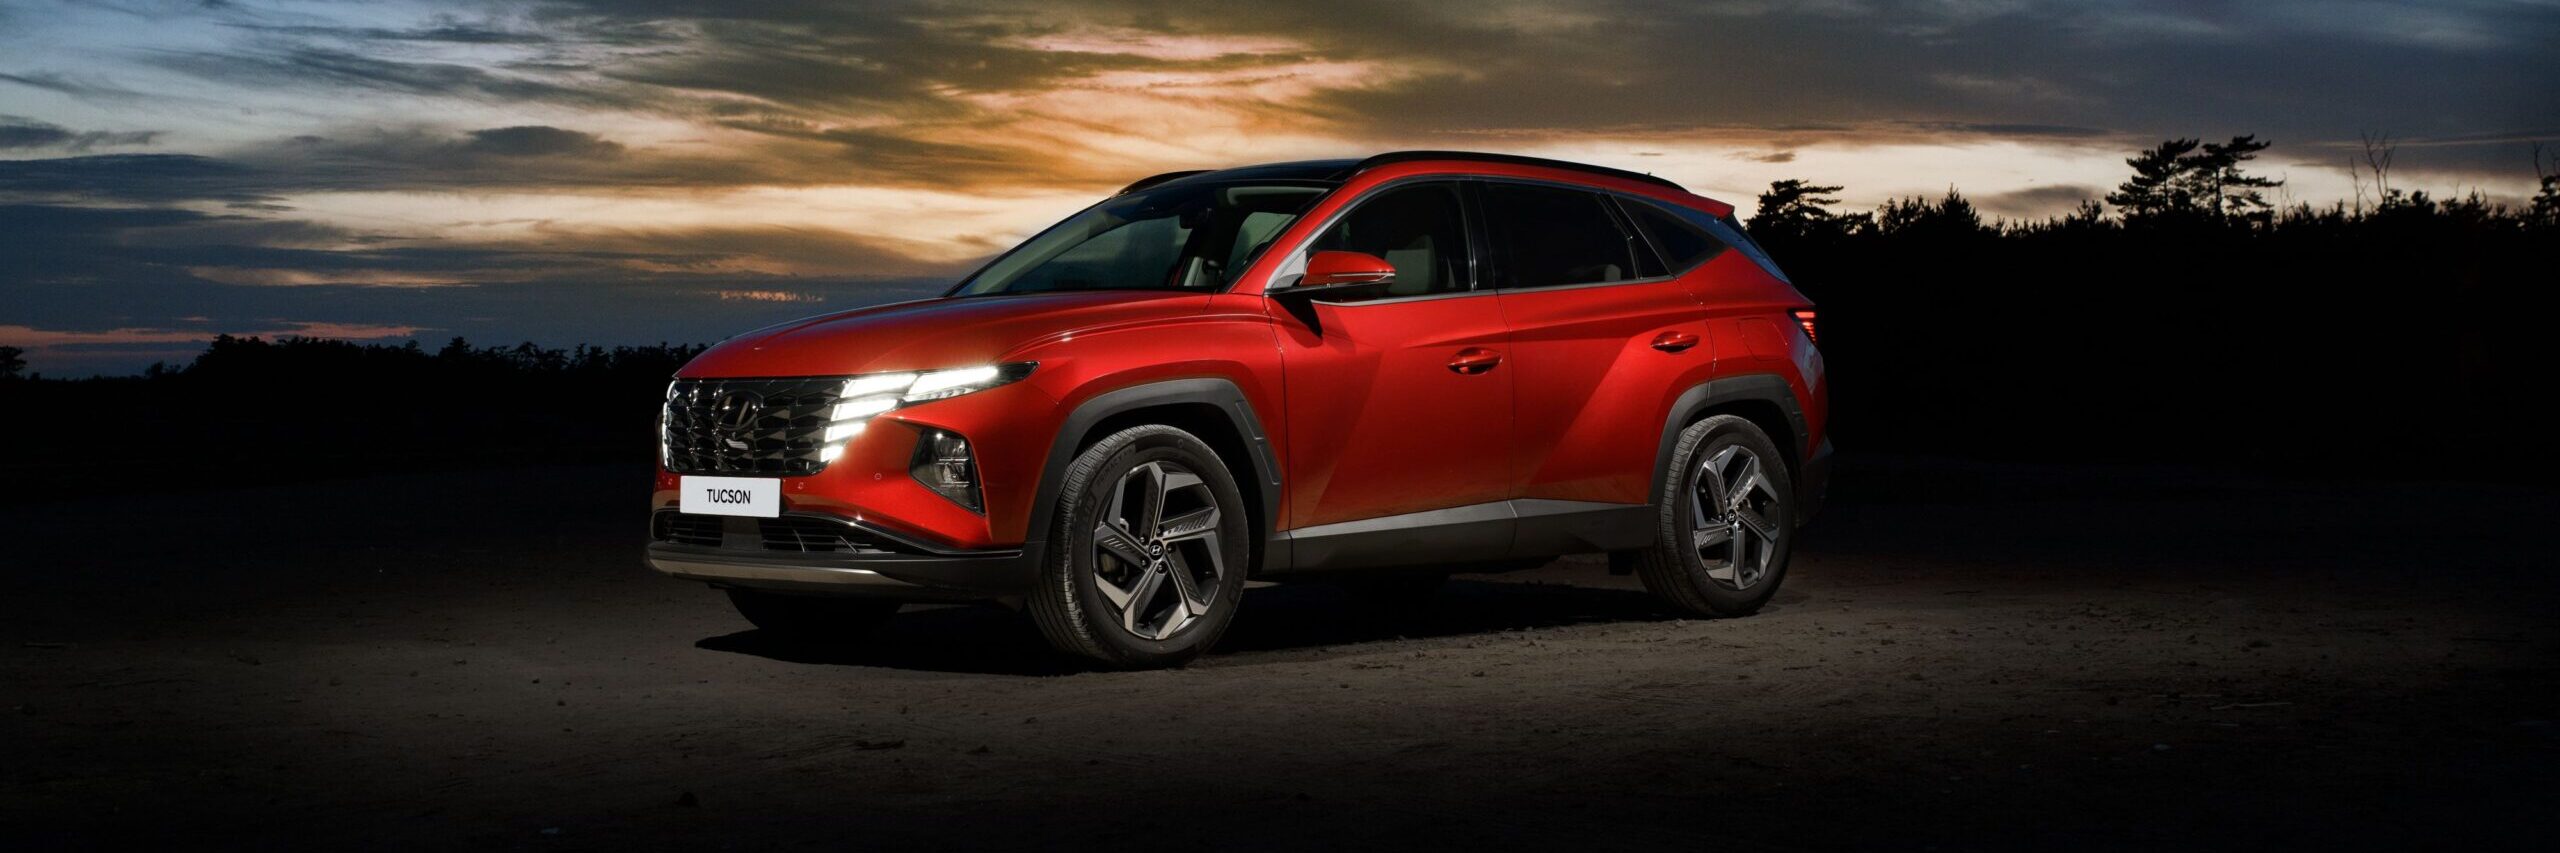
The Hyundai Tucson Car Finance page covers petrol, hybrid and plug-in hybrid choices, while Hyundai Santa Fe Car Finance is more relevant to buyers looking for a larger seven-seat SUV.
Current Hyundai car finance offers can vary between these powertrains. A plug-in hybrid may have a different promotional rate from a self-charging hybrid or petrol model, so use the quote for the exact version you want.
Used Hyundais can still benefit from remaining warranty
A used Hyundai may still have part of its original five-year unlimited-mileage warranty left, provided the warranty conditions have been met.
That can make a two or three-year-old car more attractive to someone who wants manufacturer cover without paying the price of a new vehicle.
Before arranging Hyundai car finance on a used car, check the service history, MOT record, mileage, tyre condition, previous repairs and remaining warranty. For an EV, review the battery warranty and available battery-health information too.
Visit Car Finance FAQs for more general guidance on deposits, rates and agreement types.
Compare the offer around how you will use the car
Hyundai PCP can suit drivers who want end-of-term choices. Personal Motor Loan is more focused on ownership and removes mileage restrictions, while Contract Hire works for drivers who plan to return the vehicle.
The five-year warranty, EV battery cover and changing manufacturer incentives give Hyundai buyers more to compare than the advertised monthly payment.
Before choosing Hyundai car finance, check the deposit, APR, Hyundai contribution, term, monthly payments, mileage conditions, total amount payable and any Optional Final Payment.
Enjoy Finance provides information about vehicle funding and may link to third-party providers. Any quote, application or agreement is supplied by the relevant third party and remains subject to its own eligibility, affordability checks and terms.
FAQs
What finance options does Hyundai offer?
Hyundai Finance currently offers Personal Contract Purchase, Personal Motor Loan and Personal Contract Hire for private customers, alongside business finance products.
Does Hyundai offer 0% finance?
Yes. Hyundai runs 0% APR promotions on selected models at certain times. Deposit requirements, terms and model eligibility vary, so check the live offer for the exact vehicle you want.
Can I finance a used Hyundai?
Yes. Finance can be available for used Hyundais through different providers. Vehicle age, mileage and value, together with your financial circumstances, can affect the products and rates offered.
How long is Hyundai’s warranty?
New Hyundai cars currently come with a five-year unlimited-mileage manufacturer warranty. High-voltage batteries are covered separately for eight years or 100,000 miles, whichever comes first.
Is Hyundai Personal Motor Loan the same as PCP?
No. Personal Motor Loan has no Optional Final Payment or agreed mileage limit. You make fixed payments and own the car after the final required payment. PCP leaves part of the cost until the end and gives you several options at that point.