A McLaren can sit anywhere from the used 570S market to a new Artura, 750S or seven-figure collector car, so the funding structure can change dramatically with the model. McLaren car finance can spread the cost, but buyers should pay close attention to the balloon payment, warranty cover, expected mileage and how the lender values the exact car.
Enjoy Finance explains vehicle funding and links to third-party providers. We do not provide finance directly, and the website contains affiliate links.
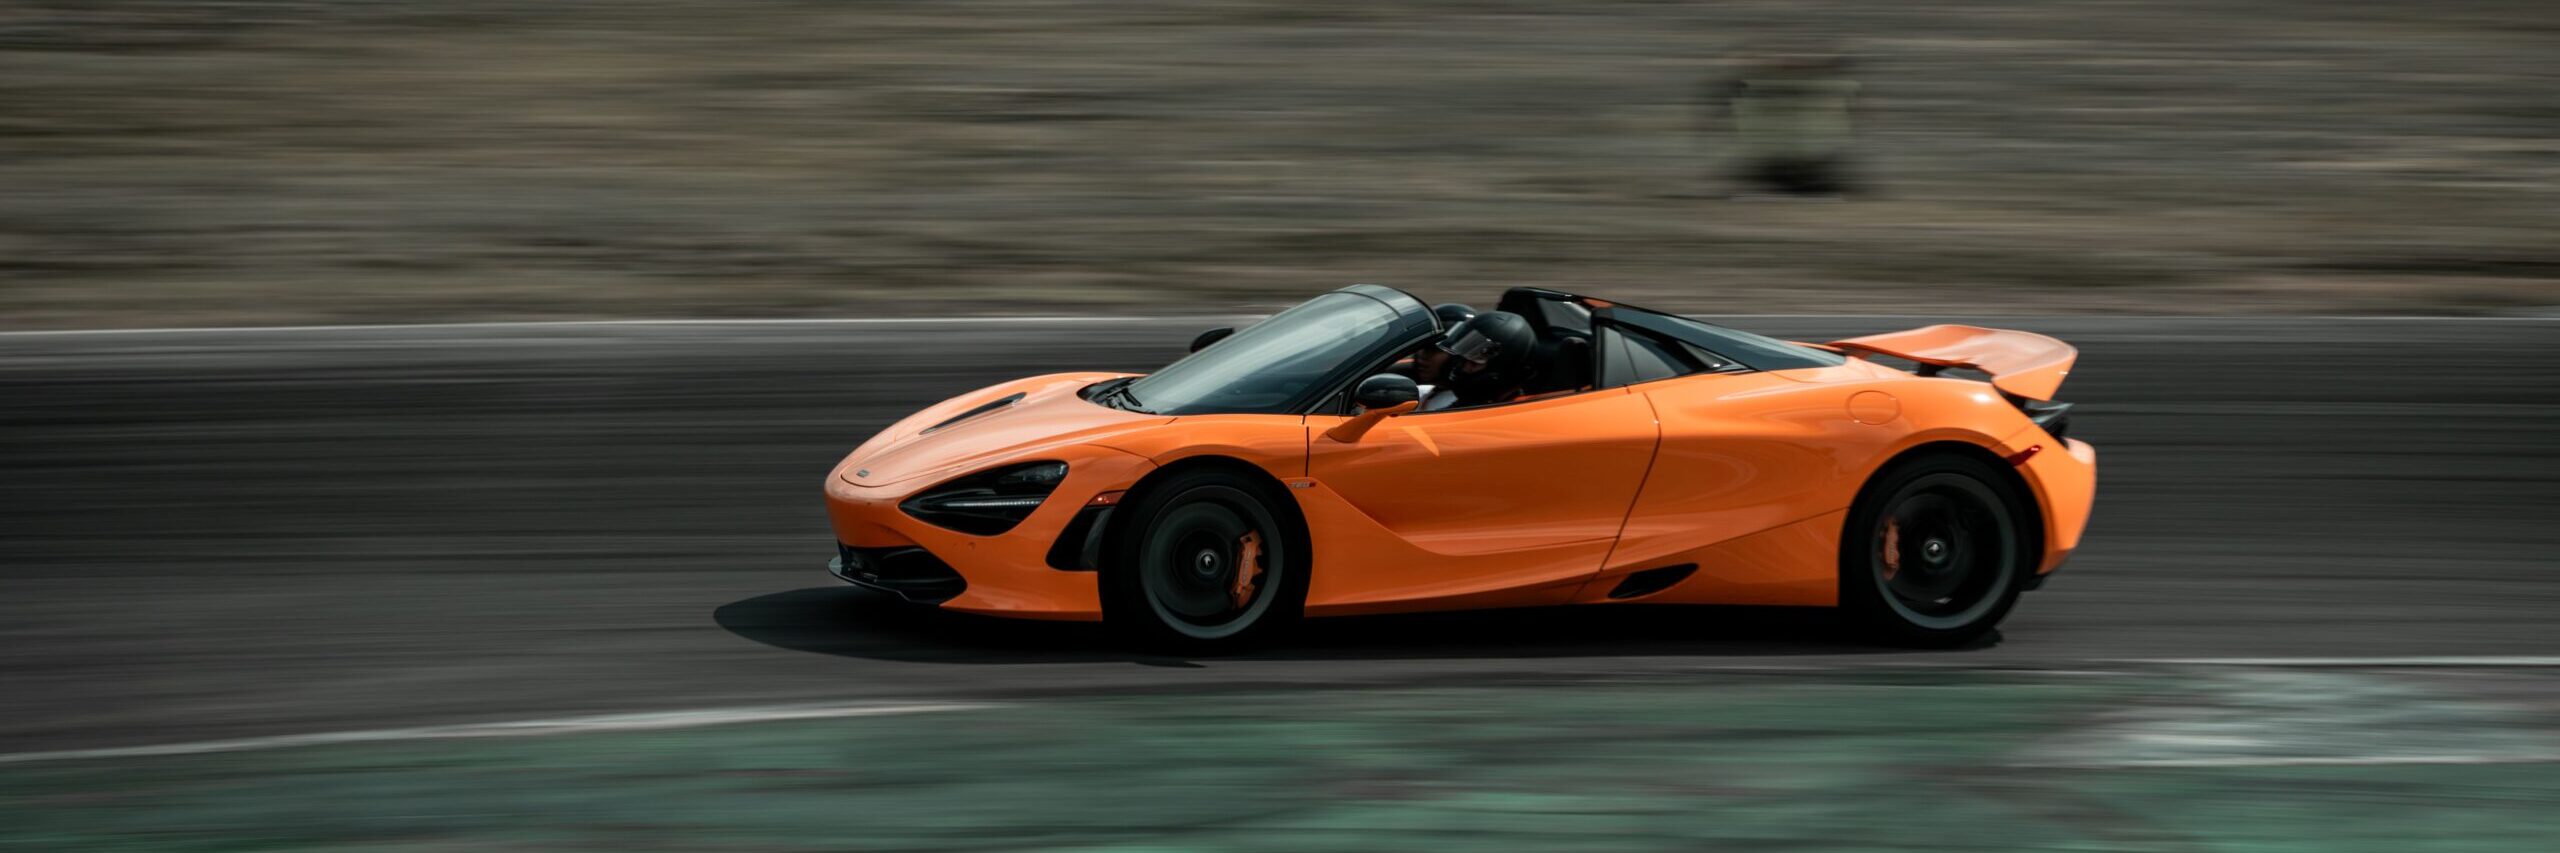
How does McLaren car finance work?
McLaren Automotive acts as a credit broker rather than a lender. Official retailers can introduce customers to finance providers, while specialist supercar lenders also offer Hire Purchase, Personal Contract Purchase and Lease Purchase-style agreements.
Vehicle value matters just as much as income and credit history. A lender may look at price, deposit, specification, age, mileage and likely future value before deciding how much it is prepared to advance.
Lease Purchase can leave a large balloon at the end
Lease Purchase is common in specialist supercar finance because it allows part of the vehicle cost to be deferred into a final balloon payment.
You make a deposit and fixed monthly payments, then settle the balloon at the end. Unlike PCP, there is normally no simple hand-back option, so the final payment needs a clear plan.
A larger balloon can reduce the regular monthly commitment, but it also leaves more outstanding later. Specialist lenders tend to base the balloon on their view of the car’s likely future trade value rather than simply trying to make the monthly figure look low.
Current specialist examples for a £100,000 McLaren GT show how significant that final payment can be, with a £20,000 deposit and a balloon exceeding £50,000 after four years.
PCP transfers more of the future-value decision to the lender
Personal Contract Purchase also leaves an Optional Final Payment, but the end-of-term choices are different.
You can usually pay the final amount and keep the car, part-exchange it after settling the finance, or return it subject to mileage and condition rules.
That return option can appeal to buyers who are cautious about future supercar values. McLaren values can move differently between models and generations, so positive equity should never be assumed.
Read Personal Contract Purchase for a wider explanation of PCP.
Artura and 750S need different funding assumptions
The current McLaren range includes the hybrid Artura, the 750S and GTS, alongside the limited-production W1 at the top of the line-up.
The McLaren Artura Car Finance page is relevant to buyers considering McLaren’s high-performance hybrid. Battery technology, warranty cover and future used demand may all influence how a lender approaches the car.
Used buyers can also visit McLaren 720S Car Finance and McLaren 765LT Car Finance. These cars sit in different parts of the used market, so the same deposit and balloon assumptions should not automatically be carried across.
When comparing McLaren car finance, the valuation of the exact model matters more than a generic brand-wide monthly figure.
Ultimate Series cars sit in a separate category
Cars such as the P1, Senna, Speedtail and W1 are not ordinary used-supercar finance cases.
Rarity, provenance, specification and collector demand can have a much larger effect on value. Specialist lenders may consider equity release or refinancing against an existing high-value vehicle, allowing an owner to release capital without selling the car.
That does not mean these cars always rise in value. Collector markets can change, and finance should not be based on an assumption of appreciation.
For a highly limited McLaren, an independent valuation and a lender familiar with collector cars can be more useful than a standard online finance calculator.
High-net-worth underwriting can look beyond a salary
Financing a six-figure McLaren can involve a more detailed affordability assessment than a mainstream car application.
Specialist lenders may look at salary, dividends, business income, investment income, liquid assets and existing commitments. Company directors and entrepreneurs can have irregular income patterns that do not fit a simple monthly-payslip assessment.
This is one reason specialist supercar lenders remain relevant, although approval, deposit requirements and rates still vary by applicant.
Warranty cover deserves a place in the finance decision
New McLarens currently come with a three-year unlimited-mileage vehicle warranty.
For used cars, the McLaren Qualified programme includes at least 12 months of McLaren Qualified Warranty, with the option to extend to 24 months. Qualified cars also receive roadside assistance, provenance checks and a McLaren inspection.
McLaren also offers extended warranty cover for qualifying cars beyond the original warranty period.
That matters when arranging McLaren car finance over three or four years. A used 720S or GT buyer may want to compare the cost of extended cover with running the car outside warranty while payments are still due.
The McLaren GT Car Finance page is useful for buyers considering a model that is now mainly found in the used market.
Older performance models need careful inspection
The used market includes 570S, 600LT, 620R, 720S and other discontinued models at very different price points.
The McLaren 620R Car Finance page covers one of the rarer Sports Series derivatives.
Before arranging McLaren car finance on any used example, check the service record, provenance, mileage, tyre condition, previous repairs, accident history and remaining warranty. Cars with extensive carbon-fibre options or unusual specifications can also carry very different replacement and repair costs.
An inspection by a McLaren specialist can be particularly useful on an older car outside the manufacturer warranty.
Compare liquidity as well as monthly payments
A £25,000 deposit and a large balloon may make the monthly figure manageable, but both affect how much cash remains available elsewhere.
Some buyers prefer to place more money upfront and reduce borrowing. Others choose a higher balloon to retain liquidity during the agreement. Neither approach is automatically cheaper.
Before choosing McLaren car finance, compare the deposit, APR, term, monthly payments, balloon, total amount payable and likely warranty costs.
Car Loans gives another ownership-focused route to compare, although ordinary personal-loan limits may be less suitable for higher-value McLarens.
Enjoy Finance provides information about vehicle funding and may link to third-party providers. Any quote, application or agreement is supplied by the relevant third party and remains subject to its own eligibility, affordability checks and terms.
FAQs
Is Lease Purchase common for a McLaren?
Yes. Specialist supercar lenders frequently offer Lease Purchase, which uses fixed monthly payments and a final balloon. Unlike PCP, the customer normally needs to settle or refinance that balloon rather than simply returning the car.
Can I get McLaren car finance on a used vehicle?
Yes. Finance can be available on used McLarens through retailer-introduced and specialist providers. Vehicle value, age, mileage and your financial circumstances can affect the terms.
Does McLaren offer PCP?
PCP can be available through McLaren retailers and specialist finance providers. It combines a deposit, monthly payments and an Optional Final Payment, with end-of-term choices subject to the agreement.
How long is McLaren’s new-car warranty?
New McLarens currently come with a three-year unlimited-mileage vehicle warranty. McLaren Qualified used cars receive at least 12 months of Qualified Warranty, with an extension option on qualifying vehicles.
Can I refinance a collectible McLaren?
Specialist lenders can offer refinancing or equity-release products against qualifying high-value cars. The amount available depends on the vehicle valuation, ownership position and the lender’s assessment.
