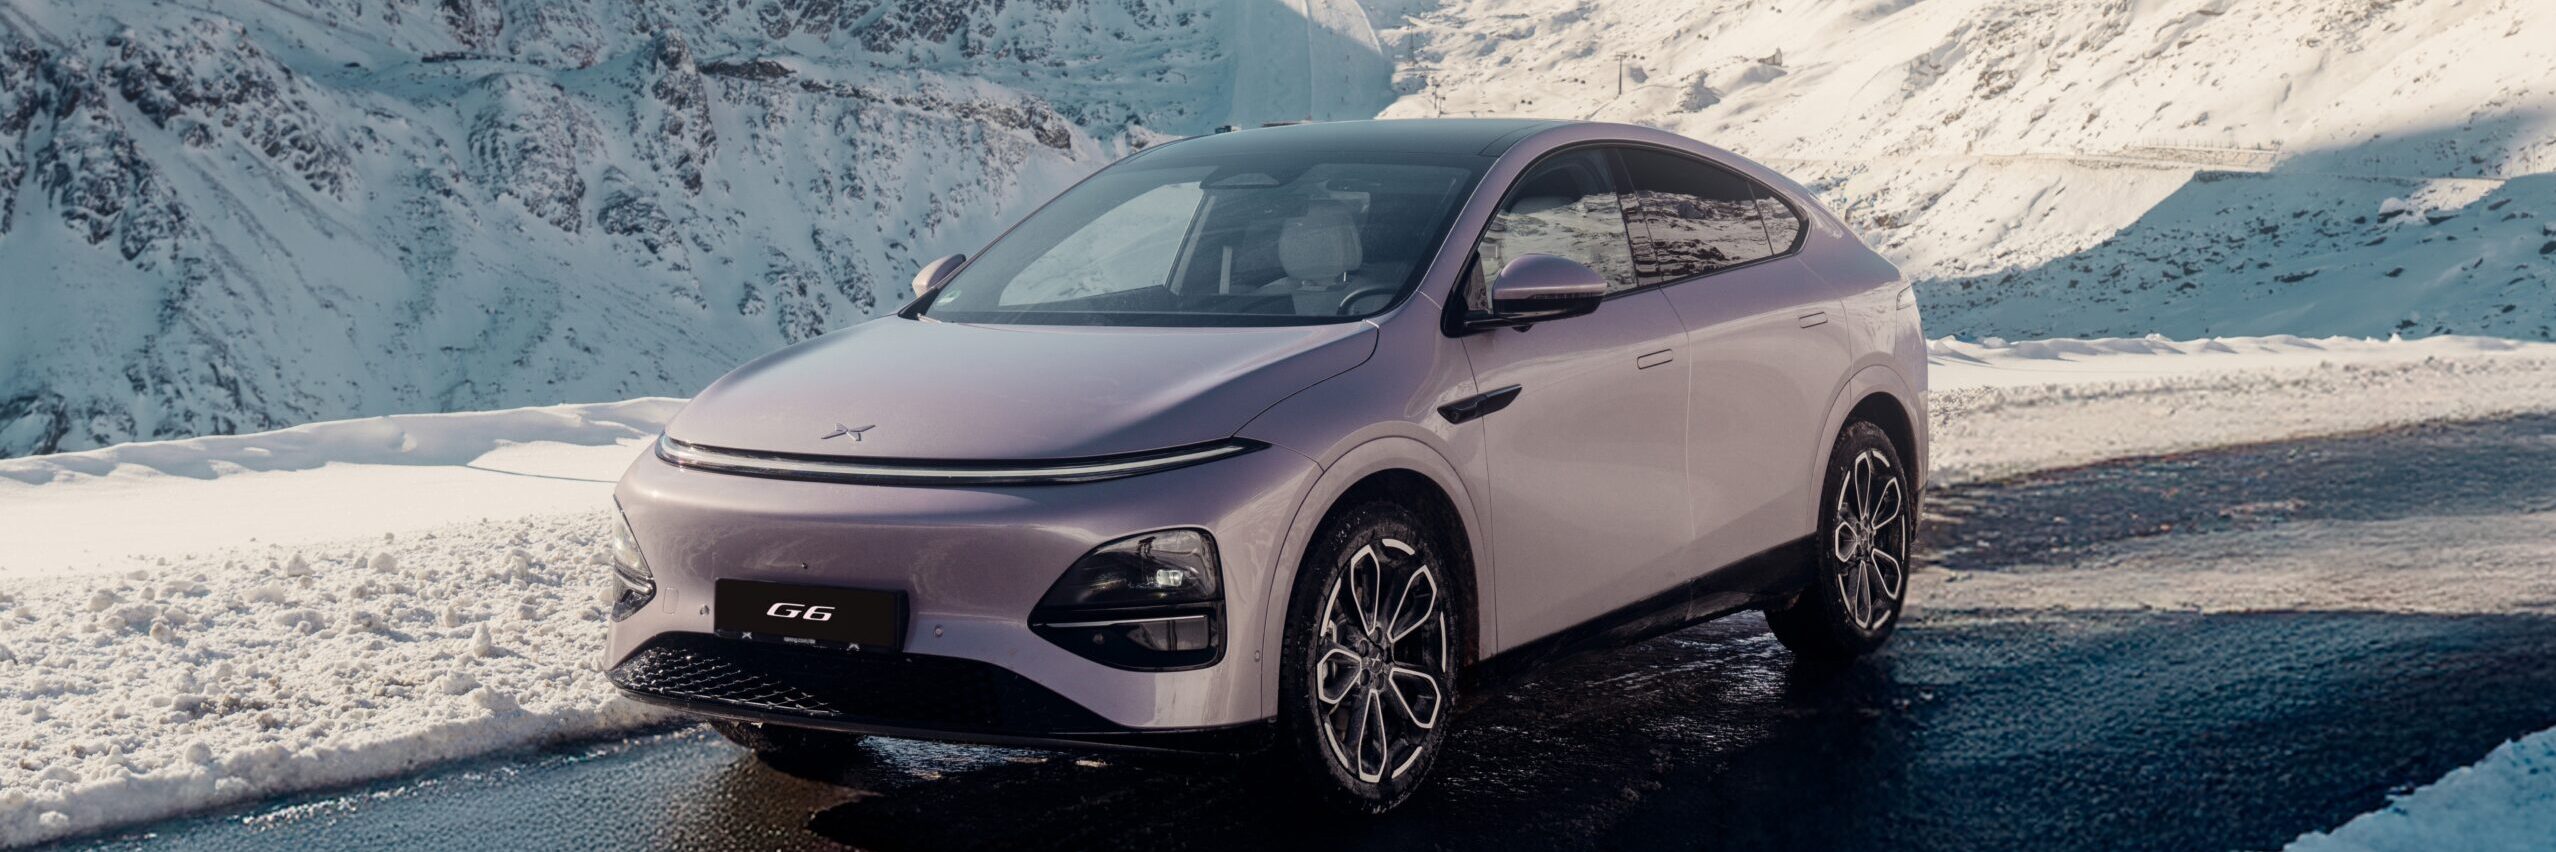
XPENG has entered the UK with a clear focus on electric cars, software and high-speed charging. Its G6 electric SUV combines premium positioning with technology normally associated with more expensive EVs, while current manufacturer offers give buyers several ways to fund one. When comparing XPENG car finance, look beyond the monthly repayment and consider your deposit, annual mileage, charging habits, agreement type and how long you expect to keep the vehicle.
How XPENG Car Finance works
There are several ways to structure XPENG car finance, including Personal Contract Purchase, Hire Purchase and leasing.
PCP divides the cost between a deposit, monthly repayments and an Optional Final Payment. HP spreads more of the vehicle cost across the agreement and is focused on eventual ownership. Personal Contract Hire works differently, as you rent the vehicle for an agreed term and return it afterwards.
The right choice will depend on your monthly budget and plans for the car. Our car finance guide explains the main agreement types in more detail.
The G6 is the main UK starting point
The G6 sits at the centre of XPENG’s current UK offering. It is a fully electric coupe-style SUV aimed at drivers looking at premium electric family cars.
Different G6 versions offer different battery capacities, performance and driving ranges. That means XPENG car finance should be compared using the exact version you want rather than a generic G6 monthly price.
The cost of a Standard Range model, for example, creates a different XPENG car finance calculation from the Long Range or all-wheel-drive Performance version.
Check the cash price, deposit and final payment for the exact specification before comparing two quotations.
PCP can suit changing EV technology
Personal Contract Purchase can appeal to drivers who want to change their electric car every few years.
With PCP, you normally pay an initial deposit followed by fixed monthly repayments. Part of the car’s value is deferred to the Optional Final Payment.
At the end, you can usually:
- Pay the Optional Final Payment and keep the vehicle
- Return it subject to mileage and condition terms
- Part-exchange it, subject to settlement and any new finance approval
This structure can be particularly relevant to XPENG car finance because electric car technology continues to move quickly.
Battery performance, charging speed, software and new-car pricing can all affect demand for used EVs. PCP gives you an agreed final payment at the start rather than requiring you to predict what the vehicle will be worth several years later.
Our Personal Contract Purchase guide covers the structure in more detail.
Current 0% finance deserves a closer look
XPENG has used 0% APR representative offers on the G6 across both PCP and Hire Purchase.
A 0% rate means no interest is charged on the financed amount under that agreement, but that does not mean every XPENG car finance quote will have the same overall structure.
The required deposit can vary considerably between PCP and HP. PCP can also leave a substantial Optional Final Payment if you decide to keep the car.
When comparing XPENG car finance offers, check:
- On-the-road price
- Customer deposit
- Representative APR
- Monthly repayment
- Number of repayments
- Optional Final Payment
- Annual mileage
- Excess mileage charge
- Total amount payable
A lower monthly payment can sometimes be created by putting considerably more money down at the beginning, so compare the whole agreement rather than one figure.
Hire Purchase for drivers who want to keep the car
Hire Purchase offers another route for XPENG car finance.
HP normally starts with a deposit before the remaining balance is repaid through monthly instalments. Once all required payments have been made under the agreement, ownership transfers to you.
There is no large Optional Final Payment in the way there normally is with PCP.
That can make HP worth comparing if you plan to keep the G6 for several years after the agreement has finished. The trade-off is that monthly repayments may be higher, or the agreement may require a larger deposit.
Read our HP car finance guide if ownership is one of your main priorities.
Fast charging changes how you might use the car
Charging performance is one of the more distinctive parts of XPENG ownership.
The latest G6 uses an 800V electrical platform and can charge from 10% to 80% in as little as 12 minutes when conditions and charger output allow.
That can make an electric car more practical for drivers who regularly cover longer distances, but the fastest possible charging figure should not be treated as what you will receive at every charger.
When budgeting for XPENG car finance, think about where you expect to charge most often.
Home charging can produce a very different monthly energy cost from relying heavily on public rapid charging. Your electricity tariff, annual mileage and access to off-street parking can all affect the overall ownership cost.
Leasing avoids the ownership decision
Not every driver wants to own the car at the end.
Personal Contract Hire allows you to pay an initial rental followed by monthly rentals across an agreed period. You then return the vehicle, subject to the mileage and condition requirements.
XPENG’s UK leasing arrangements are supported through XPENG UK Leasing, a trading style of Lex Autolease.
PCH could suit someone comparing XPENG car finance who knows they want to move into another vehicle after a few years.
There is no option to buy the vehicle through a standard PCH agreement, so this route should be compared with PCP if you want to keep that possibility open.
Think about software as part of ownership
XPENG puts more emphasis on vehicle software than many traditional manufacturers.
Its cars use connected systems, driver assistance technology and over-the-air software updates. Updates can change or improve supported vehicle functions without every update requiring a workshop visit.
For someone considering XPENG car finance over three or four years, this can form part of the ownership picture.
It is still worth checking exactly which functions are included with the UK vehicle you are ordering. Features offered in other markets are not automatically available in Britain, and driver assistance systems still require the driver to remain responsible for the vehicle.
Warranty cover and your agreement term
The latest UK G6 comes with five years or 75,000 miles of manufacturer vehicle warranty cover, whichever comes first. The high-voltage battery has separate cover for up to eight years or 100,000 miles.
This means a typical three or four-year XPENG car finance agreement on a new G6 can sit within the original vehicle warranty period, provided the mileage and warranty requirements are met.
Warranty becomes particularly relevant if you intend to keep the car after the finance has ended.
If used XPENG models become part of your search, check the registration date, mileage, servicing history and remaining battery and vehicle cover before agreeing finance.
Set the mileage around real journeys
PCP and leasing agreements normally include an annual mileage allowance.
Think about commuting, family journeys, business travel, weekends away and longer motorway trips before setting that figure.
Choosing a lower mileage allowance can make XPENG car finance appear cheaper each month, but excess mileage charges can apply if the vehicle is returned above the agreed total.
Someone buying a G6 as their main family vehicle could cover very different mileage from someone using it mainly for a short commute.
Use the mileage you realistically expect rather than choosing a figure purely to reduce the quotation.
Premium EV depreciation matters
The G6 sits in a part of the market where buyers may also be comparing cars from established premium and electric-focused manufacturers.
Electric vehicle values can change as manufacturers alter new-car prices and newer battery or charging technology reaches the market.
When assessing XPENG car finance, think about who carries that future-value risk.
If you buy through HP and eventually own the car, its resale value becomes your concern. With PCP, returning the vehicle is normally one of your end-of-term choices, subject to the mileage, condition and agreement requirements.
This difference can matter if you like XPENG’s technology but are unsure whether you will want to own the same EV several years from now.
What affects the finance offered?
XPENG may run manufacturer promotions, but approval and the exact XPENG car finance terms offered will still depend on the finance provider and your circumstances.
Factors can include:
- Credit history
- Income
- Existing financial commitments
- Deposit
- Amount being financed
- Agreement length
- Vehicle specification
Work out what you can comfortably afford alongside charging, insurance and servicing rather than focusing only on the advertised monthly payment.
Our guide to what you need to finance a car covers some of the information that may be requested during an application.
FAQs
Can I get 0% finance on an XPENG?
XPENG currently promotes 0% APR representative PCP and HP on selected G6 agreements. Offers can change, so check the live customer deposit, agreement length, monthly repayments and total amount payable before applying.
Can I lease an XPENG G6?
Yes. Personal Contract Hire is available for the G6 through XPENG UK Leasing. You pay an initial rental followed by fixed monthly rentals before returning the vehicle at the end, subject to the agreement’s mileage and condition terms.
How long is the XPENG G6 warranty?
The latest UK G6 has a five-year or 75,000-mile vehicle warranty, whichever comes first. The high-voltage battery has separate cover for eight years or 100,000 miles, subject to the manufacturer’s terms.
Compare the whole ownership cost
XPENG’s combination of premium pricing, electric power and very fast charging makes the finance decision slightly different from buying a conventional petrol or diesel car.
When comparing XPENG car finance, look at the deposit, APR, monthly payments, Optional Final Payment, mileage allowance and total amount payable. Add your expected charging costs, insurance, warranty position and likely ownership period before deciding which structure fits.
Someone planning to change EVs regularly may approach XPENG car finance differently from a driver intending to keep the G6 well beyond the agreement.
Enjoy Finance provides information about vehicle funding and may link to third-party providers. We do not provide finance directly. Applications remain subject to the relevant provider’s eligibility requirements, affordability assessment and terms.