Perodua left the UK new-car market more than a decade ago, so buying one today means looking at an older used vehicle rather than a current manufacturer offer. Perodua car finance is therefore less about promotional PCP rates and more about whether a lender will fund the exact car, how much you need to borrow and whether Hire Purchase or a personal loan makes more sense.
Enjoy Finance explains vehicle funding and links to third-party providers. We do not provide finance directly, and the website contains affiliate links.
How does Perodua car finance work?
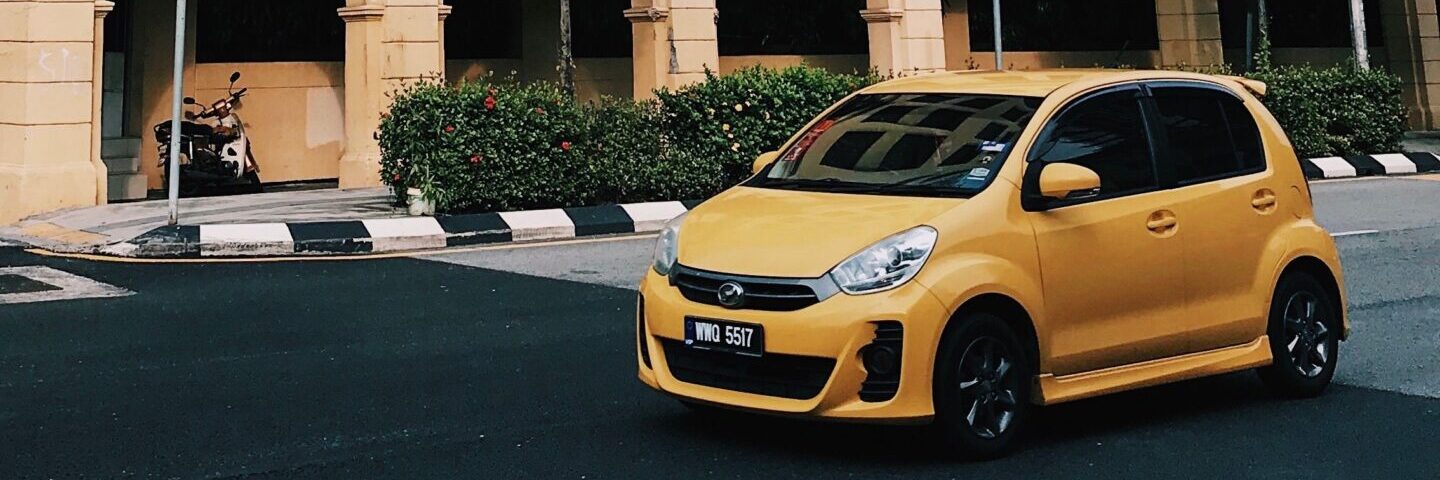
Perodua stopped importing new cars into the UK in 2014, with the Myvi the final model sold here. Perodua UK Limited was later dissolved in July 2024, so there is no current manufacturer-backed UK finance programme.
Most buyers are now looking at older Myvi, Kelisa, Kenari or Nippa models sold through independent dealers and private sellers. The finance available depends heavily on the age, value and condition of the individual car.
Vehicle age can narrow the lender choice
Many vehicle-finance providers set their own maximum age rules. That matters because even the newest UK-market Peroduas are now well over ten years old.
A lender that accepts a five-year-old hatchback may not accept a 2012 Myvi or a much older Kelisa. Others may consider older cars if the value, condition and applicant fit their criteria.
For Perodua car finance, check lender eligibility against the actual registration rather than assume every older car will be rejected.
Hire Purchase can suit an older low-value car
Hire Purchase can be one of the more straightforward ways to fund a used Perodua when a lender accepts the vehicle.
You normally pay a deposit, then repay the financed amount plus interest through fixed monthly instalments. After the required payments and any purchase fee have been completed, ownership passes to you.
There is no large Optional Final Payment and no mileage allowance linked to returning the car. That can suit someone buying a Myvi or Kelisa as a long-term runaround.
Read What is HP Car Finance? for more detail.
A personal loan may make more sense at this price point
The remaining UK Perodua market is inexpensive compared with most modern used cars. Current Myvi listings can sit below £2,000, which changes the finance calculation.
Some vehicle lenders have minimum advance amounts that can make small HP agreements impractical. A personal loan may be worth comparing because the borrowing is separate from the vehicle and can also allow you to buy from a private seller.
Car Loans explains this route in more detail.
When comparing Perodua car finance, look at the total amount repayable rather than choosing purely on the smallest monthly figure. Extending a small loan over too many years can make the interest cost disproportionate to the value of the car.
PCP is unlikely to be the natural fit
Personal Contract Purchase is built around an Optional Final Payment based on the expected future value of the vehicle.
That structure is easier to use on newer cars with strong market data. An older Perodua worth only a few thousand pounds gives the lender less room to create a meaningful balloon.
That does not mean PCP is impossible, but buyers should not expect a manufacturer-backed Perodua PCP offer.
Personal Contract Purchase explains how the structure normally works.
Do not assume nil-deposit finance will be available
Deposit requirements vary between providers. A lender may ask for a deposit, restrict the minimum amount borrowed or shorten the term because of the car’s age. The applicant’s credit profile and affordability also affect the rate and structure.
For Perodua car finance, a £35 or £50 monthly payment should not be treated as a realistic brand-wide benchmark. The useful figure is the full cost of borrowing on the exact agreement offered.
Parts availability needs to be part of the buying decision
Perodua originally committed funding to parts and servicing support after leaving the UK, but that programme was designed for the years immediately following the 2014 withdrawal.
Parts can still be sourced through independent UK suppliers and breakers, with Myvi, Kelisa, Kenari and Nippa components still listed. Availability can vary considerably by component.
Before financing a car, check the condition of body panels, suspension, exhaust, cooling system and electrical components. A low purchase price can quickly lose its appeal if a hard-to-find part leaves the vehicle off the road.
The Myvi is the easiest model to find
The Myvi was the final Perodua officially sold in Britain and remains the model most commonly seen in current used listings.
That makes it easier to compare asking prices than rarer Kenari, Kelisa or Nippa examples. Even so, service history, corrosion, MOT record, tyres and previous repairs can matter more than a small difference in purchase price.
Before arranging Perodua car finance, use the registration number to check MOT history and confirm that the car’s condition justifies borrowing against it.
Credit profile matters more than the badge
There is no reliable Perodua-wide APR. The rate depends on the lender, amount borrowed, term and applicant’s circumstances.
Older-car finance can sometimes cost more because the lender is advancing money against a low-value asset with limited resale value. Compare providers rather than assuming a high rate is unavoidable.
What is a good car finance rate? explains some of the factors that can affect borrowing costs.
Compare the finance with the remaining life of the car
A long agreement on a very old car needs careful thought. If the vehicle needs a major repair halfway through the term, you could still be making payments while deciding whether the repair is financially sensible.
Before choosing Perodua car finance, compare the deposit, APR, term, monthly payment, fees and total amount repayable. Then add insurance, servicing, MOT work and a realistic repair allowance.
What are the different types of car finance? and Car Finance FAQs provide more general guidance.
Enjoy Finance provides information about vehicle funding and may link to third-party providers. Any quote, application or agreement is supplied by the relevant third party and remains subject to its own eligibility, affordability checks and terms.
FAQs
Can I still finance a Perodua in the UK?
Potentially. Independent lenders and used-car dealers may finance an older Perodua, but vehicle age, value and the applicant’s circumstances can affect eligibility.
Does Perodua still sell new cars in the UK?
No. Perodua stopped importing new cars into the UK in 2014, so buyers are now looking at used vehicles rather than a current manufacturer range.
Can I get PCP on a used Perodua?
It may be possible through an independent provider, but PCP is unlikely to be the natural option for an older, low-value car. HP or a personal loan can be more practical.
Is a personal loan better than HP for a cheap Perodua?
It can be worth comparing. A personal loan may suit a low-value purchase or private sale, while HP keeps the borrowing linked to the vehicle. Compare the APR, term and total repayable.
Are Perodua parts still available in the UK?
Yes, some independent suppliers and breakers still stock parts for models including the Myvi, Kelisa, Kenari and Nippa. Availability depends on the exact component.
