Morgan ownership is unusual because the cars themselves are unusual. A new Plus Four, Super 3 or Supersport is hand-built in relatively small numbers, while older Morgans can vary sharply in age, specification and value. Morgan car finance therefore needs to account for more than the monthly payment, particularly where deposits, annual mileage and final payments are substantial.
Enjoy Finance explains vehicle funding and links to third-party providers. We do not provide finance directly, and the website contains affiliate links.
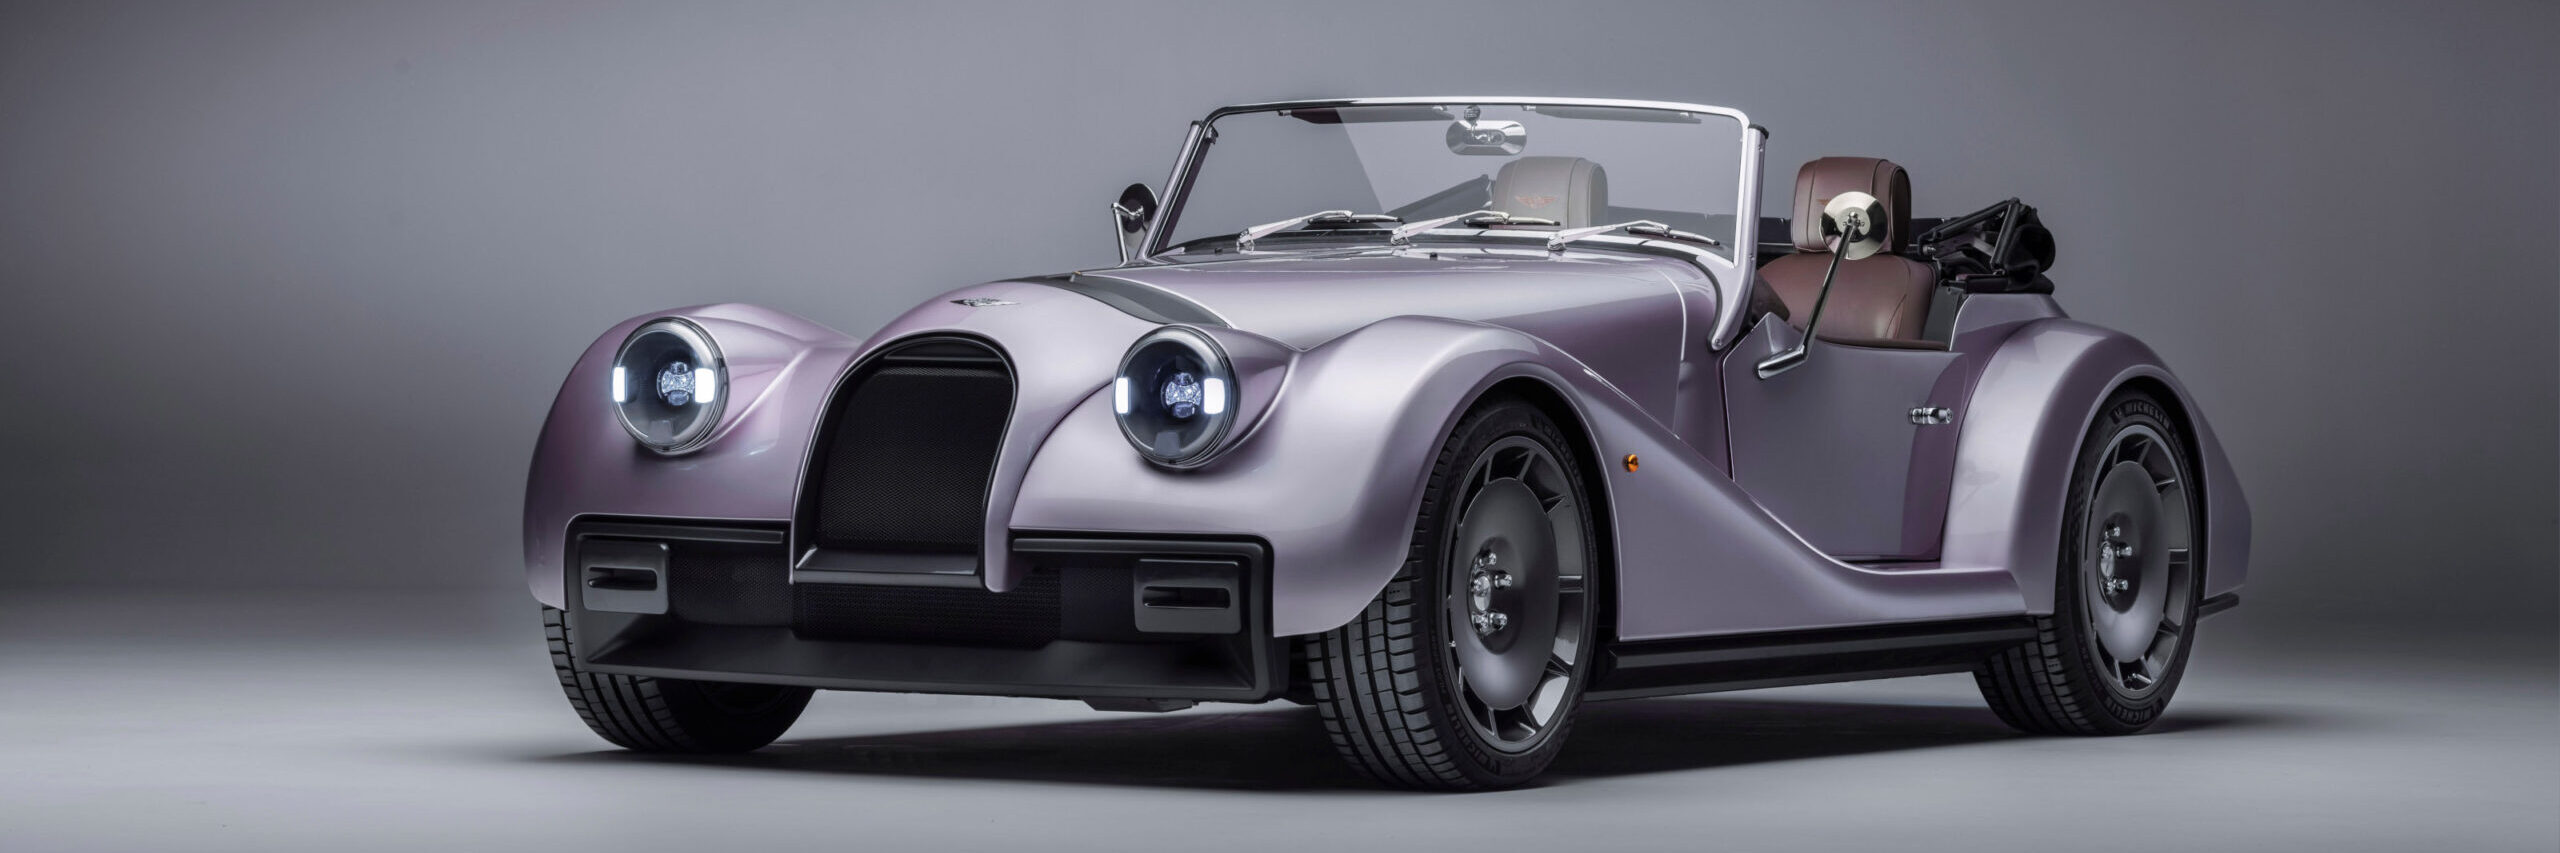
How does Morgan car finance work?
Official manufacturer funding is provided by CA Auto Finance UK Limited trading as Morgan Motor Finance. Morgan currently presents Personal Contract Purchase, Advance Payment Plan, Hire Purchase and used-car finance through its dealer network.
The structure that suits you depends on whether you want to keep the car, how many miles you expect to cover and how much cash you are comfortable committing at the start.
PCP keeps a large part of the value until the end
Morgan’s PCP examples use a customer deposit, fixed monthly payments and an Optional Final Payment. The expected future value of the car is set when the agreement starts.
At the end, you can pay the final amount and keep the vehicle, part-exchange it after settling the agreement, or return it subject to mileage and condition requirements.
That can make PCP attractive on a high-value, low-volume sports car, but buyers should not assume that a Morgan will always appreciate or hold a particular percentage of its purchase price.
Read PCP Car Deals for a broader explanation.
Current Morgan examples use low annual mileage assumptions
Morgan’s official finance pages currently display 2026 PCP examples calculated at 5,000 miles a year.
The Super 3 example carries a 16p-per-mile excess charge, the Plus Four example 29p per mile and the Supersport example 44p per mile. That creates a real distinction between a car bought for occasional weekends and one intended for regular European touring.
Before choosing Morgan car finance, estimate mileage honestly. A lower monthly payment based on 5,000 miles a year can become less attractive if you expect to cover double that.
The headline APR varies by model
The finance research should not treat 9.9% as a fixed Morgan-wide rate. The official pages currently show 9.9% APR PCP examples for the Super 3 and Plus Four, while the Supersport and Supersport 400 examples use 6.9% APR.
Those published examples relate to cars ordered between 1 April and 30 June 2026 and registered by 30 September 2026. Buyers placing a new order now should request a fresh quotation rather than assuming the displayed campaign still applies.
The Morgan Plus Four Car Finance page provides more model-specific information.
Advance Payment Plan changes the cash-flow pattern
Morgan’s Advance Payment Plan is one of the more unusual parts of its finance offering.
Instead of making regular monthly payments, the customer places a large deposit and leaves an Optional Final Payment until the end of a short agreement. Current published examples use a 50% deposit and a 12-month term.
The Supersport and Supersport 400 campaign examples show 0% APR on this structure, while the Plus Four and Super 3 examples shown on Morgan’s site use 9.9% APR.
For Morgan car finance, APP therefore should not be described as automatically interest-free across the range. Check the exact model, order date and quotation.
Supersport finance involves much larger sums
Morgan’s Supersport sits in a different financial bracket from the Super 3.
One published PCP example uses an on-the-road price of £119,048, a customer deposit of £29,054.72 and an Optional Final Payment of £69,293. The Supersport 400 example moves higher again.
Large final payments can make the regular monthly figure look more manageable, but the amount due at the end still needs a clear plan.
If you intend to keep the vehicle, compare PCP with What is HP Car Finance? before deciding.
Used and classic Morgans need individual valuation
The pre-owned market includes Plus 4, Roadster, Aero 8, Plus Six and much older cars alongside nearly new Plus Four and Super 3 examples.
Older Morgans can be difficult to value using ordinary mass-market assumptions. Age, chassis condition, bodywork, provenance, engine, restoration quality and originality can all affect price.
The Morgan Plus Six Car Finance page is relevant to buyers looking at the discontinued six-cylinder model.
When arranging Morgan car finance on a classic or specialist used example, ask how the lender values the car and whether any independent inspection or valuation is required.
Specialist funding can suit cars outside ordinary PCP criteria
Prestige and specialist lenders can offer alternatives for older, modified or unusually valuable cars that do not sit neatly within manufacturer finance.
Lease Purchase is one possible structure. It can leave a large balloon payment until the end, which can reduce regular repayments. Unlike a PCP return option, the final balloon usually needs to be paid, refinanced or cleared through sale of the car.
Mileage conditions and deposit requirements vary by provider, so they should be checked rather than assumed.
For another ownership-focused route, Car Loans explains unsecured borrowing.
Touring mileage can change the best finance route
A Morgan used for summer weekends has a very different finance profile from one driven across France, Italy or the Alps each year.
High touring mileage can make a low-mileage PCP less suitable, particularly where excess charges are significant. HP, a personal loan or a specialist balloon structure may give a different balance between monthly cost and ownership.
Morgan car finance should therefore follow how you intend to use the car, not simply the lowest advertised monthly payment.
Compare the deposit, mileage and final payment together
The most useful comparison is the full agreement.
Check the customer deposit, APR, monthly payment, annual mileage allowance, excess-mileage charge, total amount payable and Optional Final Payment. Then add insurance, servicing, tyres, storage and any warranty costs that sit outside the agreement.
What is a good car finance rate? and Car Finance FAQs provide wider guidance.
Enjoy Finance provides information about vehicle funding and may link to third-party providers. Any quote, application or agreement is supplied by the relevant third party and remains subject to its own eligibility, affordability checks and terms.
FAQs
Who provides Morgan finance in the UK?
CA Auto Finance UK Limited currently trades as Morgan Motor Finance and provides the manufacturer-backed finance products promoted through participating Morgan retailers.
Does Morgan currently offer 0% finance?
Morgan’s published 2026 examples include 0% APR Advance Payment Plan offers on the Supersport and Supersport 400. Those examples were tied to specific order and registration dates, so current availability should be checked with a dealer.
Can I get Morgan car finance on a used car?
Yes. Used-car finance is available through Morgan dealers and independent providers. The terms can depend on the car’s age, value, specification and the applicant.
What mileage are Morgan PCP examples based on?
The current published Super 3, Plus Four and Supersport PCP examples use 5,000 miles a year. Excess-mileage charges differ by model.
Is Lease Purchase available for older Morgans?
It can be available through specialist providers. Lease Purchase normally leaves a final balloon that has to be settled or refinanced, so buyers should check the exact agreement carefully.
