MINI offers compact hatchbacks, crossovers and electric models, so the way you fund one can depend on how you plan to use the car. Mini car finance can spread the cost across an agreed term, with routes for drivers who want flexibility, eventual ownership or a car they can change after a few years.
Enjoy Finance explains the main options and links to third-party providers. We do not provide finance directly, and the website contains affiliate links.
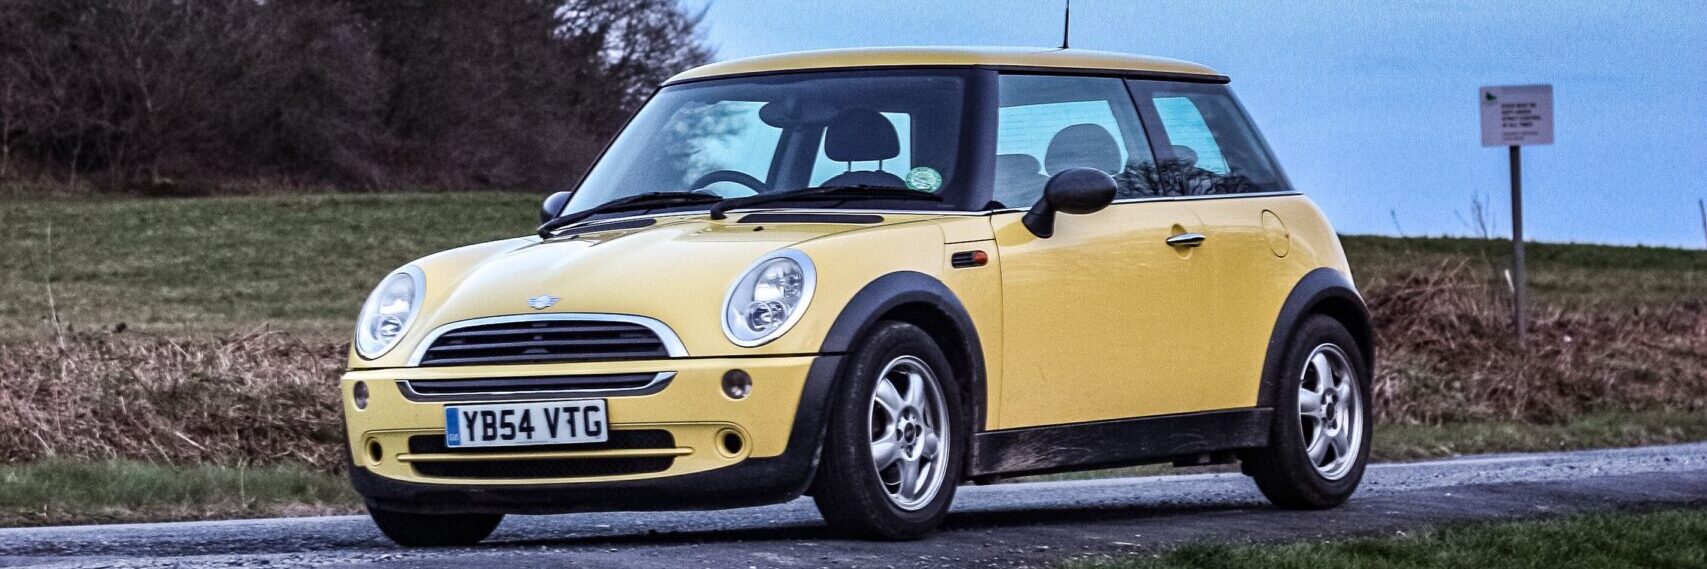
How does Mini car finance work?
Most agreements begin with a deposit or initial payment followed by monthly repayments. The amount you pay can vary with the model, purchase price, term, expected mileage, interest rate and any final payment.
For a MINI, the choice often comes down to MINI Select PCP, Hire Purchase, Contract Hire or another loan-based route. A driver using a Cooper for city journeys may value flexibility, while someone buying a used Countryman for several years may care more about long-term ownership.
MINI Select PCP
MINI Select is the manufacturer’s Personal Contract Purchase product and is available for new and Approved Used MINIs. You choose a deposit, a term between 24 and 48 months and an expected annual mileage.
MINI then sets an Optional Final Payment based on what it expects the car to be worth at the end. Deferring that amount can reduce the regular monthly payment compared with an equivalent Hire Purchase agreement, although it can increase the total interest paid.
At the end, you can pay the Optional Final Payment and keep the MINI, part-exchange it for another vehicle, or return it subject to mileage and condition requirements.
Read How does PCP Finance work? or explore PCP Car Deals for more information.
Hire Purchase for drivers who want to keep their MINI
Hire Purchase is more focused on ownership. You normally pay a deposit and repay the financed amount plus interest through fixed monthly instalments.
There is no large Optional Final Payment reducing the regular repayments, so the monthly figure can be higher than on a comparable PCP agreement. Once all required payments have been made, the car becomes yours under the agreement terms.
This can suit someone buying a MINI they expect to keep for longer, especially a used model. Enjoy Finance’s What is HP Car Finance? guide explains the structure in more detail.
Petrol or electric MINI finance?
The current MINI range includes petrol and fully electric choices. The Cooper is available with petrol and electric powertrains, the Aceman is fully electric, and the Countryman is available in petrol and electric versions.
Electric buyers may focus more closely on charging access, annual mileage and future vehicle value. Petrol buyers may place more weight on fuel costs and how long they expect to own the car.
When comparing Mini car finance for an electric model, include home or public charging costs in the monthly budget rather than looking only at the finance payment.
Check current MINI finance offers
MINI regularly runs model-specific promotions, including low-rate PCP, different deposit requirements, Contract Hire offers and incentives on selected electric cars.
The exact terms change, so a rate available on a Cooper may not apply to an Aceman or Countryman. Some promotions can also require a higher minimum deposit or shorter agreement term.
When reviewing Mini car finance, compare the APR, deposit, monthly payment, total amount payable and Optional Final Payment together. What is a good car finance rate? explains more about factors that can influence the rate offered.
MINI Service Inclusive and ownership costs
Servicing is another part of the budget worth checking before signing an agreement.
MINI Service Inclusive lets owners pay a fixed amount for scheduled servicing across an agreed period or mileage allowance. Promotions sometimes offer it at a reduced fixed price on new petrol and electric models, but the cost and cover can change.
Insurance, tyres, charging or fuel, vehicle tax where applicable and repairs outside the package should still be included in your budget.
With Mini car finance, looking at those costs alongside the monthly repayment gives a more realistic picture of what the car will cost to run.
Financing a used MINI
Used MINIs give buyers plenty of choice, from older Cooper and Countryman models to newer Approved Used cars.
Before financing one, check its age, mileage, service history, MOT record, tyre condition and any remaining warranty. The vehicle’s age and value can also affect which providers and products are available.
MINI runs Approved Used and Young Used promotions at different times, including finance offers on selected electric cars. These can change, so compare manufacturer-backed funding with other routes rather than assuming one will always cost less.
If outright ownership is the priority, Car Loans provides another overview of vehicle borrowing.
Contract Hire if ownership is not the goal
Personal Contract Hire can suit drivers who want to use a new MINI for a fixed period and return it afterwards.
You pay an initial rental followed by monthly rentals based on the vehicle, term and agreed mileage. There is no option to buy the MINI through the Contract Hire agreement.
Excess mileage charges can apply if you exceed the allowance, so choose a realistic figure. This matters for commuters who may be tempted by a lower advertised payment based on limited mileage.
Drivers comparing Mini car finance with leasing should decide early whether owning the car at the end matters to them.
Compare the whole agreement
A low monthly figure can be attractive, but it should not be the only part of the decision. Check the deposit, APR, term, mileage allowance, monthly payments, total amount payable and any Optional Final Payment.
You can also visit Car Finance FAQs for more guidance on common finance questions.
Enjoy Finance provides information about MINI funding and may link to third-party providers. Any quote, application or agreement is supplied by the relevant third party and is subject to its own eligibility and affordability checks. If you have a question about information on the site, visit Contact Us.
FAQs
What is MINI Select?
MINI Select is MINI Financial Services’ PCP product. You choose a deposit, agreement length and annual mileage, with an Optional Final Payment left until the end. You can then keep, part-exchange or return the car subject to the agreement terms.
Can I get Mini car finance on a used car?
Yes. Finance can be available for used MINIs as well as new cars. The rate and product available can depend on the vehicle’s age, mileage, value and the provider’s criteria.
Is PCP or Hire Purchase better for a MINI?
PCP can suit drivers who want lower regular payments and choices at the end. Hire Purchase is more focused on paying towards ownership across the term. Which fits better depends on how long you want to keep the car and your budget.
Can I finance an electric MINI?
Yes. Electric MINI models can be financed through products such as MINI Select PCP and Contract Hire, subject to availability and provider terms. Charging costs and expected mileage are worth including in your comparison.
Does MINI offer low-interest finance?
MINI runs promotional finance rates on selected new and used models at different times. These deals can have specific deposit, term and order-date requirements, so check the current terms before applying.
