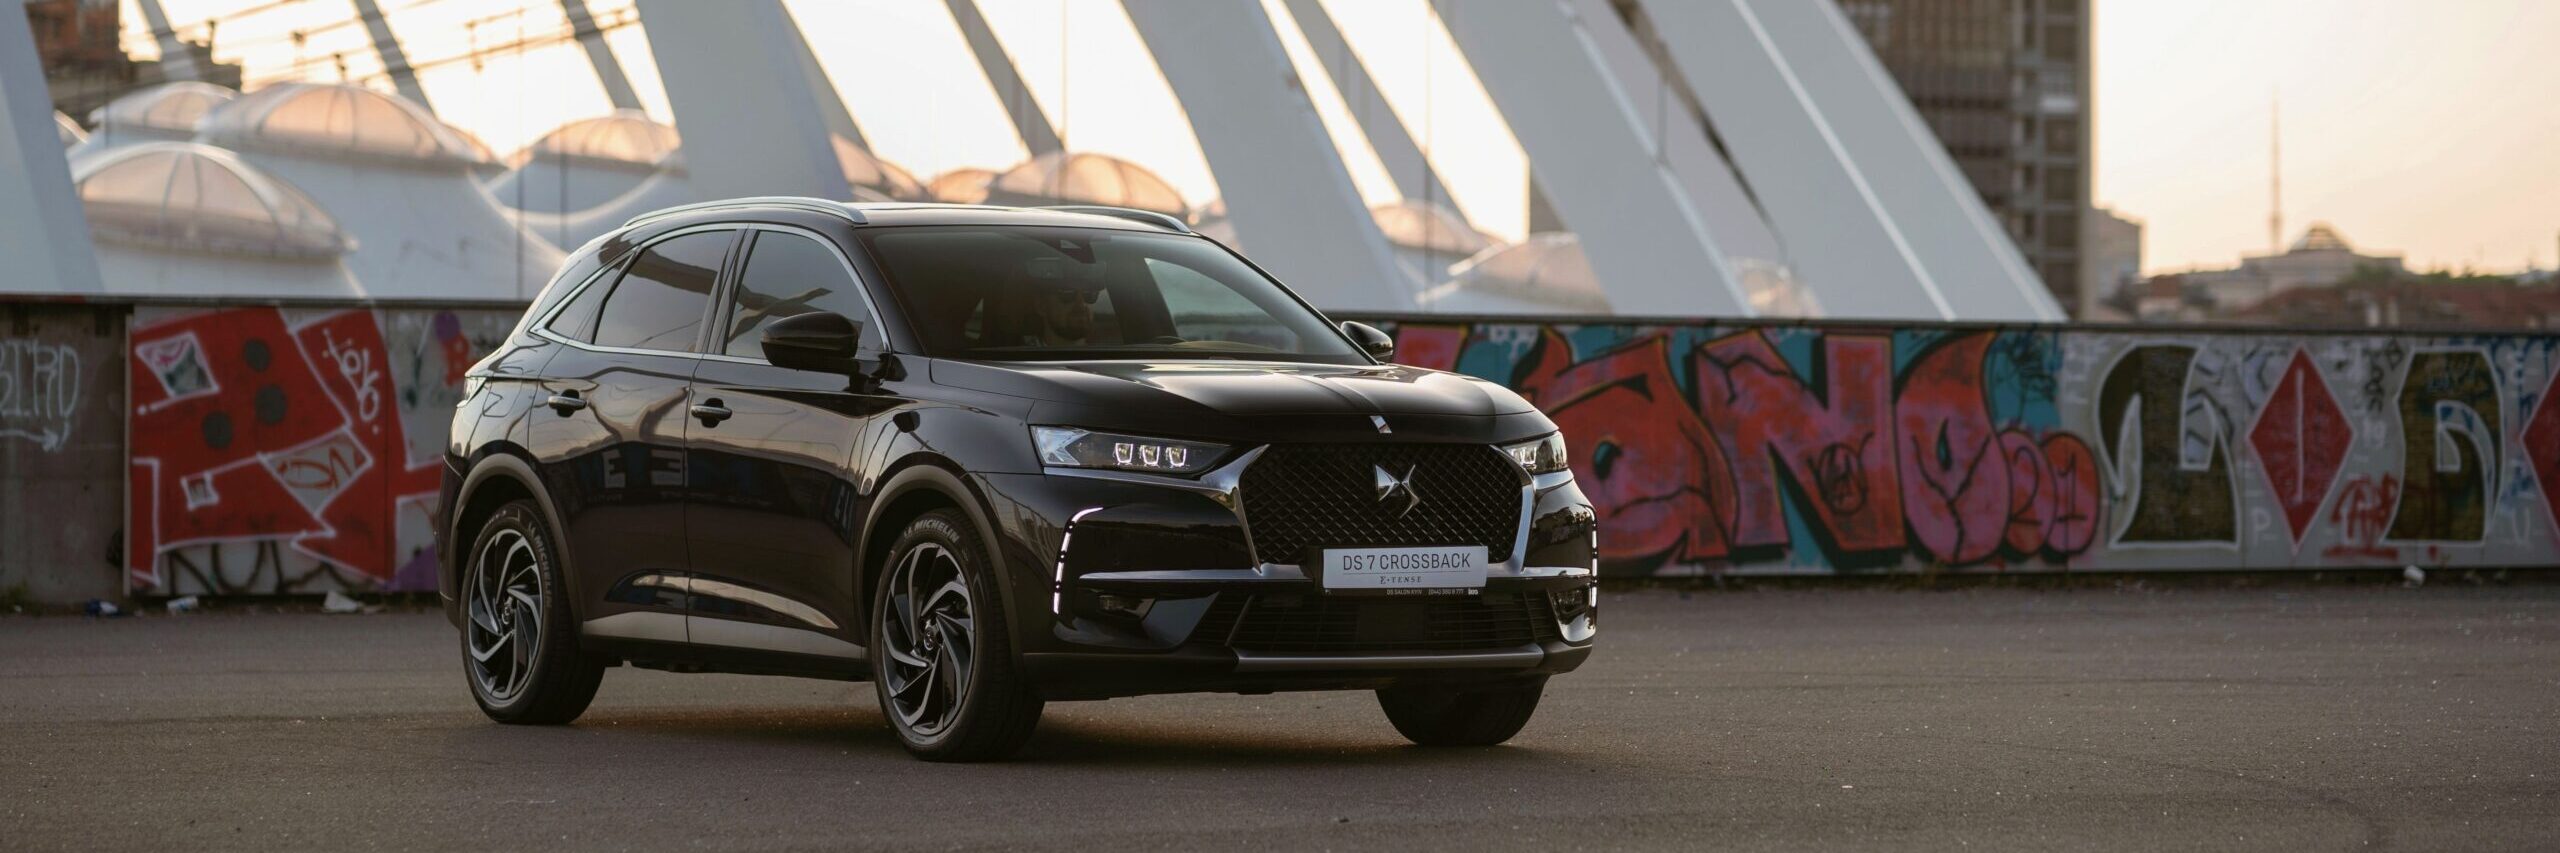
DS Automobiles blends French design with hybrid and electric technology across models such as the DS 3, N°4, N°7 and N°8. DS car finance can spread the cost while giving buyers different routes depending on mileage, deposit size, powertrain and whether they want to own the car at the end.
Enjoy Finance explains the main funding routes and links to third-party providers. We do not provide finance directly, and the website contains affiliate links.
How does DS car finance work?
DS Automobiles offers Personal Contract Purchase, Personal Contract Hire and Conditional Sale through Stellantis Financial Services. DS Automobiles acts as a credit broker rather than the lender.
PCP leaves part of the vehicle cost until the end as an Optional Final Payment. Personal Contract Hire is based on using the car for an agreed period and returning it, while Conditional Sale works towards ownership through fixed repayments.
PCP is built around flexibility
DS Personal Contract Purchase can run for two, three or four years, with deposits between 0% and 40% of the vehicle price. DS currently allows annual mileage bands between 6,000 and 30,000 miles.
The agreed mileage helps set the Guaranteed Future Value and the Optional Final Payment.
At the end, you can pay the Optional Final Payment to own the car, return it subject to mileage and condition requirements, or part-exchange it where equity is available.
That equity is not guaranteed. The vehicle’s market value at the end of the agreement can be higher or lower than the settlement figure.
Read Personal Contract Purchase for a wider explanation.
Electric incentives can change the overall deal
DS is now pushing further into electric cars through models such as the DS 3 E-TENSE, N°4 E-TENSE, N°7 E-TENSE and N°8 E-TENSE.
Current campaigns show why electric DS offers need to be checked separately from hybrid models. Selected DS 3 and N°4 Personal Contract Hire offers include a £1,500 Government Electric Car Grant, while qualifying electric models can also receive a complimentary home charger under current promotional terms.
These incentives should be treated separately from the finance itself. A grant reduces the vehicle price, while a charger offer reduces part of the cost of setting up home charging.
When comparing DS car finance on an electric model, look at the vehicle price after any qualifying grant, the initial payment, monthly cost, mileage allowance, charging access and total amount payable.
Conditional Sale suits drivers who want ownership
Conditional Sale takes a more direct route than PCP.
You pay a deposit followed by equal monthly repayments, with current DS terms running from 24 to 60 months. Once every required payment has been made, the vehicle becomes yours.
There are no annual mileage restrictions under a DS Conditional Sale agreement. That can make it relevant to drivers who cover more miles or already know they want to keep the car.
The monthly payment may be higher than on PCP because there is no large Optional Final Payment left until the end.
Drivers comparing ownership routes can also read Car Loans.
New DS models and older model names now overlap
The current range is changing quickly. DS 3 remains part of the line-up, while N°4, N°7 and N°8 represent the newer naming direction.
The used market still contains earlier DS 4, DS 7, DS 9, DS 3 Crossback and DS 7 Crossback models.
Buyers looking at those cars can visit DS 4 Car Finance, DS 7 Car Finance and DS 9 Car Finance.
The DS 3 Crossback Car Finance page is also useful for buyers considering the previous version of the compact SUV.
That split matters because DS car finance on a new N°8 electric model is a very different proposition from financing a used DS 7 or DS 9.
Personal Contract Hire removes the ownership decision
Personal Contract Hire uses an advance rental followed by fixed monthly rentals for the agreed period.
You set the annual mileage in advance, and the car is returned at the end. Excess mileage and vehicle condition charges can apply, and there is no ownership option.
That can suit someone who wants a new DS for a set period without planning for a large final payment or future resale.
Current DS electric offers also show that PCH can sometimes receive different incentives from PCP, so compare both routes using the same model and mileage.
Only You adds an ownership layer, not a finance discount
DS promotes its Only You programme as part of the wider brand experience. It gives owners access to personalised services, concierge-style support and selected privileges.
It should not be treated as a finance rebate or a reason to choose one agreement over another. The programme sits alongside the ownership experience rather than changing the APR, deposit or final payment.
DS also includes roadside assistance on new vehicles. Petrol, diesel and hybrid cars currently receive three years of cover from registration, while electric cars receive three years or 100,000 miles, whichever comes first.
For someone comparing DS car finance, that support can be included in the wider ownership calculation without confusing it with the finance cost itself.
Used DS models need a different comparison
A used DS may cost far less than a new N°8 but can still carry premium servicing, tyre and repair costs.
Before financing one, check the service history, MOT record, mileage, previous repairs, tyre condition and remaining warranty. On an electric model, review the battery warranty and available battery information as well.
Used-car APRs can also differ from new-car campaigns, so compare the total amount payable rather than assuming a lower purchase price always creates a cheaper agreement.
PCP Car Deals gives a broader comparison of PCP structures across different vehicles.
Compare the finance with the ownership experience
DS buyers are paying for more than the badge. Powertrain, specification, servicing, charging and warranty support can all change the real monthly cost.
Before choosing DS car finance, compare the deposit, APR, term, monthly payment, mileage conditions, total amount payable and any Optional Final Payment. For an electric car, add home and public charging. For a used car, add likely maintenance and warranty cover.
Enjoy Finance provides information about vehicle funding and may link to third-party providers. Any quote, application or agreement is supplied by the relevant third party and remains subject to its own eligibility, affordability checks and terms.
FAQs
Who provides DS finance in the UK?
Manufacturer-backed DS finance is provided by Stellantis Financial Services. DS Automobiles acts as a credit broker and introduces customers to the lender.
What is DS Personal Contract Purchase?
DS PCP uses a deposit, fixed monthly payments and an Optional Final Payment. At the end, you can keep the vehicle, return it subject to the agreement terms, or part-exchange it where equity is available.
Can I finance a used DS?
Yes. DS car finance can be available for used vehicles through manufacturer-backed or independent providers. Vehicle age, mileage, value and your circumstances can affect the available terms.
Does DS offer finance on electric cars?
Yes. PCP and Personal Contract Hire are available on qualifying electric DS models, with separate promotional incentives sometimes applying to electric cars.
Does Conditional Sale have a mileage limit?
No. DS states that its Conditional Sale agreements do not have annual mileage restrictions. Once all required repayments have been made, the vehicle becomes yours.