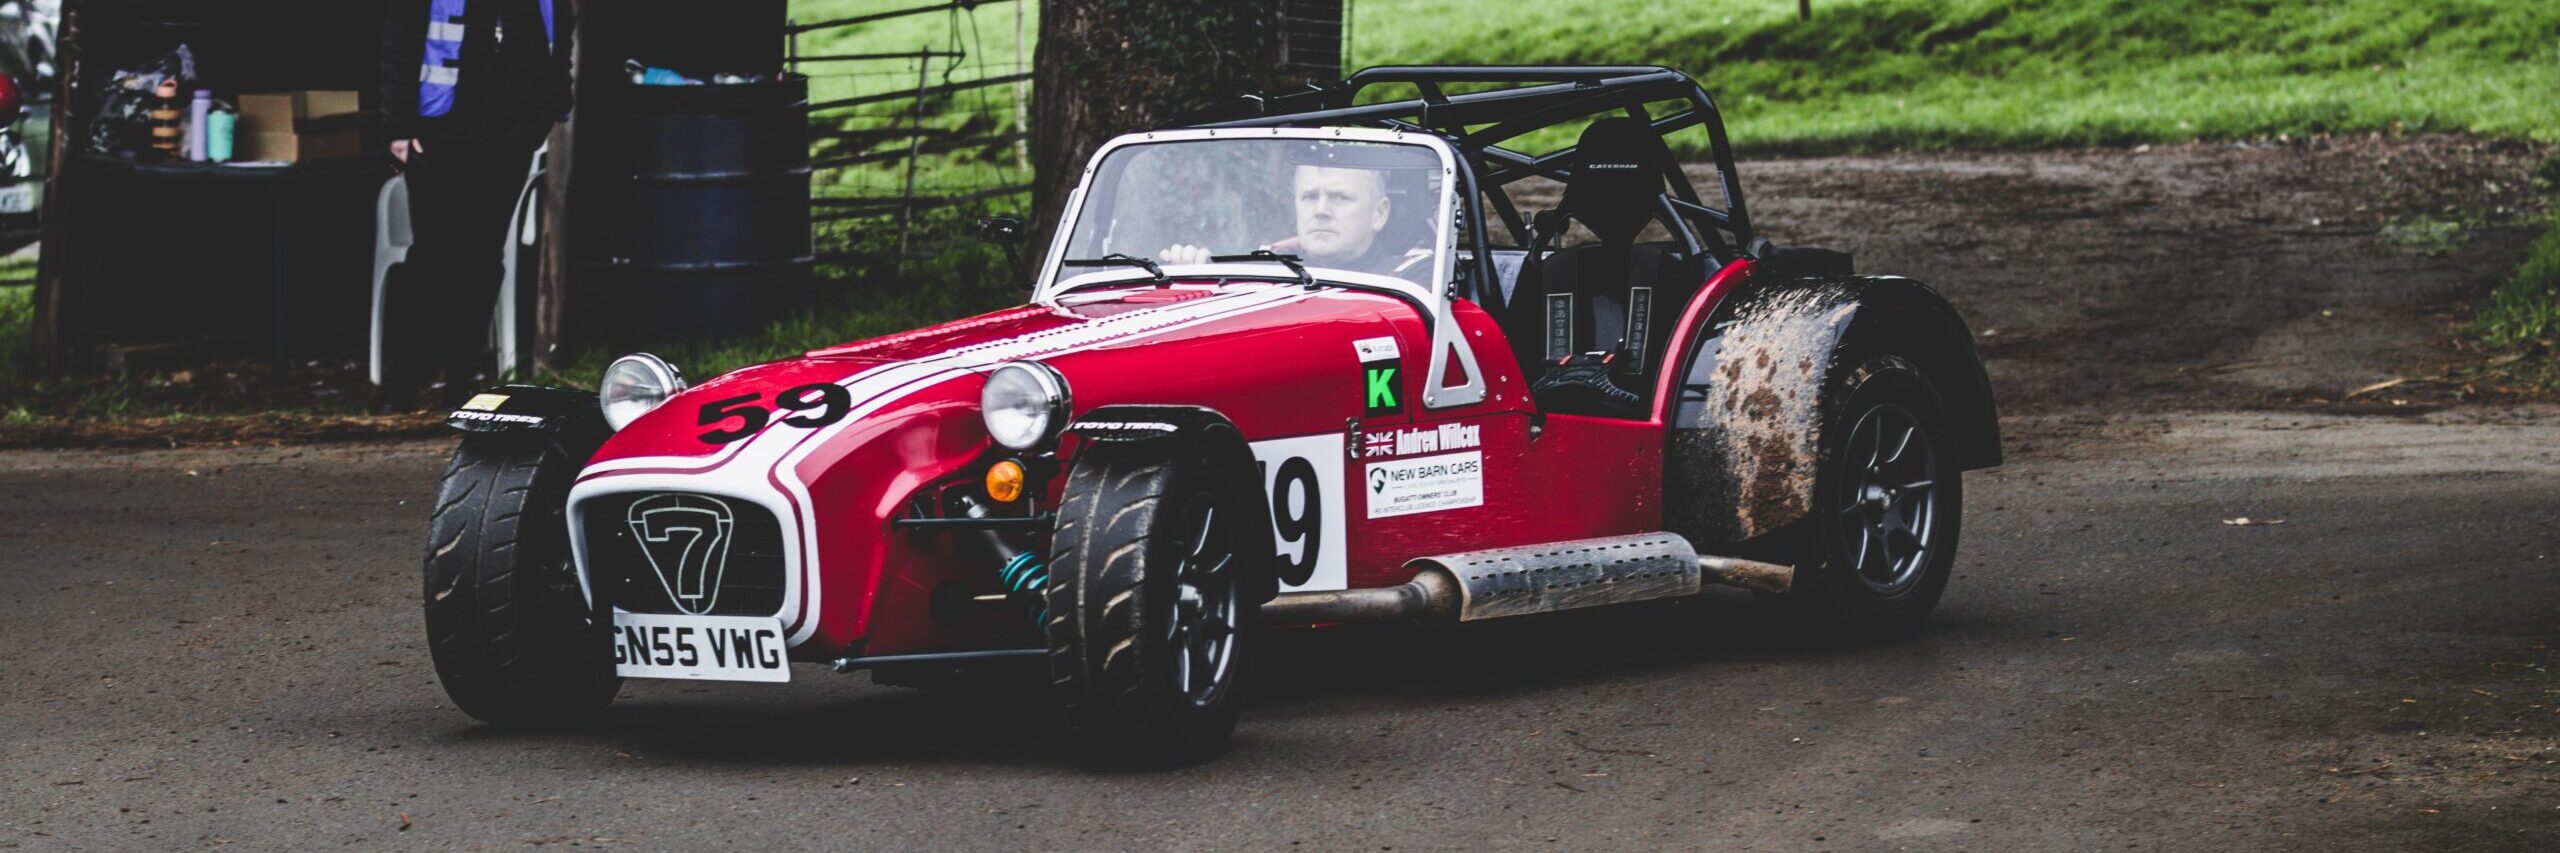
A Caterham Seven is one of the few cars that can be bought for a Sunday drive, a European road trip or a first season of competitive motorsport. Caterham car finance reflects that unusual mix. New factory-built cars now have manufacturer-backed funding, while older Sevens and race-focused cars can call for a different approach.
Enjoy Finance explains vehicle funding and links to third-party providers. We do not provide finance directly, and the website contains affiliate links.
How does Caterham car finance work?
Caterham Financial Services is operated by CA Auto Finance UK Limited. The partnership launched in 2025 and supports Caterham retailers with manufacturer-backed finance products.
The current September 2026 representative offers are mainly Conditional Sale with Balloon rather than ordinary PCP. You pay a deposit and monthly instalments, then a mandatory balloon at the end. That final payment must be settled. Returning the Seven instead is not listed as an alternative under these agreements.
Current Seven offers use a mandatory final balloon
Caterham currently publishes 36-month Conditional Sale with Balloon examples across much of the range.
A Seven 360S is shown at £259 a month with a £9,850 deposit and £29,068 final balloon. A Seven 420S is £315 a month with a £9,600 deposit and £31,545 final balloon. The detailed examples currently show 7.9% APR Representative.
Caterham’s homepage separately advertises finance on the Seven 360 and 420 from 6.9% APR Representative, so buyers should request the exact current quotation for the derivative they are ordering rather than assuming one rate applies across the range.
For Caterham car finance, the monthly figure only makes sense once the deposit and mandatory final payment are included.
Visit Caterham 7 Car Finance for more model-specific information.
Balloon finance is different from PCP
A low monthly figure can look similar to PCP because a large part of the cost remains until the end. The legal structure is different.
Under Caterham’s current Conditional Sale with Balloon examples, the balloon is mandatory. You need to pay it, refinance it or clear it through another route. There is no standard PCP hand-back option in place of paying that balance.
That makes planning important, particularly on models where the final balloon exceeds £30,000 or £40,000.
PCP Car Deals explains how conventional PCP normally works so you can compare the two structures.
The Academy can finance the start of a racing season
The Caterham Academy is one of the most unusual manufacturer-backed finance propositions in the UK.
The package includes a road-legal Caterham Seven race car to keep, a full season of racing, two exclusive practice days, the racing licence course, technical support and guidance for novice competitors.
Caterham currently offers the Academy package from £44,995. Its representative finance example uses a £22,388.82 deposit, 23 monthly payments of £335 and a mandatory final balloon of £17,998 over 24 months at 7.9% APR Representative.
This funding can cover far more than an ordinary road-car purchase. The package is built around entering the Academy championship itself.
The current finance offer requires the package to be ordered by 30 September 2026, so later entrants should check the replacement terms.
Track use needs to match the agreement
The Academy finance offer proves that circuit use is not automatically incompatible with vehicle finance. Caterham Financial Services is directly funding a road-legal race car and competition package.
That does not mean every financed Seven can be used in every track event without question. A privately financed road car may have different permitted-use conditions, while insurance for track days or competition is separate from ordinary road cover.
If you plan regular track days, sprints or racing, tell the finance provider and insurer before signing. Written confirmation is far safer than assuming the car’s track capability means the contract permits every form of motorsport.
Hire Purchase can suit drivers who want straightforward ownership
Some buyers would rather repay the full financed balance over the term without leaving a large balloon.
Hire Purchase can provide that route where available. Payments are usually higher than under a comparable balloon agreement because more of the vehicle’s cost is being repaid each month, but there is no large deferred balance to plan for at the end.
Read What is HP Car Finance? for a wider explanation.
For someone planning to keep a Seven for many years, Caterham car finance through an ownership-focused structure may be easier to budget around than a large mandatory balloon.
Older Sevens need a different lender conversation
The used Caterham market stretches back decades and includes Rover K-Series cars, Ford-powered Sevens, kit-built examples and factory-built cars.
Age, registration history, engine swaps, modifications and build quality can all affect lender appetite. A finance provider comfortable with a recent factory-built 420R may not assess a much older K-Series car in the same way.
Before arranging Caterham car finance on a used Seven, check the V5C, service history, chassis condition, engine specification, accident repairs and any track or competition history.
A Car Loans product can provide another route where conventional secured vehicle finance does not fit the car.
Do not treat residual value as guaranteed appreciation
Caterhams can have a strong enthusiast following, but that does not mean every Seven will hold its value in the same way.
Model, engine, factory specification, build quality, condition, mileage and demand all affect resale value. Limited editions may behave differently from widely available cars, while heavy modifications can either appeal to a particular buyer or narrow the market.
A large balloon should be judged against your ability to settle it, not an assumption that selling the car later will automatically cover the balance.
Compare the whole commitment before choosing
Before selecting Caterham car finance, compare the deposit, APR, monthly payments, agreement length, total amount payable and any mandatory final balloon. Then add insurance, servicing, tyres and track-day costs where relevant.
What are the different types of car finance? and Car Finance FAQs provide wider guidance.
Enjoy Finance provides information about vehicle funding and may link to third-party providers. Any quote, application or agreement is supplied by the relevant third party and remains subject to its own eligibility, affordability checks and terms.
FAQs
Who provides Caterham finance in the UK?
CA Auto Finance UK Limited trades as Caterham Financial Services and provides the manufacturer-backed finance currently promoted through Caterham retailers.
Is Caterham car finance the same as PCP?
Not necessarily. Caterham’s current representative offers are Conditional Sale with Balloon agreements. The final balloon is mandatory and the published terms do not provide a PCP-style option to return the car instead.
Can the Caterham Academy be financed?
Yes. Caterham currently publishes a finance offer for the Academy Race Car and Package, including the road-legal car and the programme for a novice racing season.
Can I use a financed Caterham on track?
Potentially, but check the specific agreement and insurance. The Academy has its own manufacturer-backed motorsport finance proposition, while other road-car agreements can have different use conditions.
Can I finance an older Caterham Seven?
Potentially. Vehicle age, registration, value, modifications and the provider’s lending criteria can affect which products are available.
