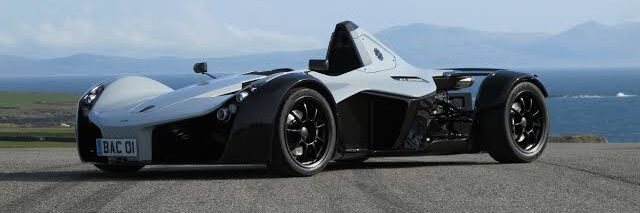
The BAC Mono is not a conventional sports car. It is a single-seat, road-legal machine built around lightweight construction, a central driving position and motorsport-derived engineering. BAC car finance sits in a specialist part of the market, where a lender may assess the individual car, its value and intended use rather than relying on a mass-market calculator.
Enjoy Finance explains vehicle funding and links to third-party providers. We do not provide finance directly, and the website contains affiliate links.
How does BAC car finance work?
BAC’s Model Year 2026 Mono is currently in production and available to order. UK buyers can speak to BAC directly or H.R. Owen BAC in Cheltenham, which acts as a credit broker rather than a lender.
There is no single published manufacturer PCP rate that should be applied to every new Mono. A buyer may instead compare Hire Purchase, Lease Purchase, a personal loan or another specialist structure according to the vehicle value and provider criteria.
Specialist underwriting can matter more than the headline APR
The current Mono weighs 580kg and produces 305bhp. It is also built in very small numbers and configured around its owner.
Those characteristics can make valuation more individual than it would be for a high-volume production car. Specialist prestige lenders can assess high-performance cars individually rather than relying entirely on an automated valuation route.
That does not mean every mainstream lender automatically rejects a BAC. Eligibility can depend heavily on the lender’s vehicle rules, the amount being borrowed and the applicant.
The BAC Mono Car Finance page provides more model-specific information.
Lease Purchase can leave a large amount until the end
Lease Purchase is often used for high-value performance cars. The buyer pays a deposit and regular instalments while leaving an agreed balloon until the end.
This can reduce the regular monthly commitment, but the balloon still has to be paid, refinanced or cleared through the sale of the vehicle. It is not the same as PCP, where returning the car can be one of the standard end options.
Specialist lender JBR Capital currently offers Lease Purchase for high-end cars over terms typically between two and five years and assesses applications individually.
For BAC car finance, the final balloon deserves as much attention as the monthly figure.
Hire Purchase provides a clearer route to ownership
Hire Purchase removes the large balloon. You normally pay a deposit and repay the financed amount through fixed instalments, with ownership passing after all required payments and any purchase fee have been completed.
Regular payments can be higher than under a comparable balloon structure because more of the vehicle cost is repaid during the agreement.
Read What is HP Car Finance? for a broader explanation.
PCP should not be assumed
The live Enjoy Finance BAC pages currently refer to PCP, but a published manufacturer-backed BAC PCP offer with a guaranteed future value could not be verified.
A PCP provider needs to set an Optional Final Payment based on the expected future value of the car. Low production numbers, individual specifications and limited used-market data can make that assessment more specialised.
If PCP is offered, compare the deposit, APR, mileage allowance, monthly payments, Optional Final Payment and return conditions.
PCP Car Deals explains how PCP normally works.
Track use needs to be agreed rather than assumed
The road-legal Mono is engineered for both road and circuit driving. BAC describes the 2026 car’s adaptive ABS as moving between road or wet settings and a track-focused setting, while H.R. Owen presents the Mono as a car for road and track.
The finance agreement is separate. Before taking a financed BAC onto a circuit, check the permitted-use conditions and ask whether track days, timed events or competition are allowed. Check the insurance policy too.
There is no reliable rule that every finance agreement is automatically cancelled when a vehicle enters a circuit. The actual contract controls what is permitted.
The Mono Cup needs to be treated separately
BAC also produces the Mono Cup Car, a dedicated track-focused model. It should not be treated as having the same finance profile as the road-legal Mono.
A competition or track-only asset may need a specialist provider because its use, registration status and resale market differ from a road car.
If motorsport use is the main reason for buying, tell the provider before agreeing BAC car finance rather than trying to fit the vehicle into a standard road-car product.
Company funding needs a genuine business case
A limited company can potentially fund a vehicle, but buying a Mono through a company does not automatically create a tax advantage.
The tax position depends on ownership, availability for private use, Benefit-in-Kind treatment and the finance structure. A high-performance petrol vehicle can also carry a substantial company-car tax cost.
The often-cited Close Brothers relationship with BAC does not prove that customers can access a special corporate Mono finance scheme. That arrangement involved BAC using asset finance to release capital from vehicles held by the manufacturer itself.
Company buyers should ask an accountant or tax adviser to assess the proposal.
Used Monos can require individual valuation
Earlier Mono generations and Mono R cars appear on the specialist used market. Specification, provenance, mileage, servicing, circuit use, accident history and factory upgrades can all affect value.
Before arranging BAC car finance on a used example, ask for detailed maintenance records and confirm how the lender has valued the individual car.
A personal loan may provide another ownership route. Car Loans explains how unsecured borrowing differs from vehicle finance.
Compare the finance with the way you will use the car
A Mono bought mainly for road driving creates a different lending and insurance conversation from one that will spend regular weekends on a circuit.
Before choosing BAC car finance, compare the deposit, APR, term, monthly payment, total amount payable and any final balloon. Add insurance, servicing, tyres, circuit transport and any specialist storage or track-day costs.
What are the different types of car finance? and Car Finance FAQs provide wider guidance.
Enjoy Finance provides information about vehicle funding and may link to third-party providers. Any quote, application or agreement is supplied by the relevant third party and remains subject to its own eligibility, affordability checks and terms.
FAQs
Can I finance a new BAC Mono in the UK?
Potentially. The 2026 Mono is available to order, and H.R. Owen BAC can act as a credit broker. The lender and product offered will depend on the vehicle, amount being borrowed and applicant.
Is Lease Purchase available for a BAC Mono?
Specialist high-end vehicle lenders offer Lease Purchase, so it can be a relevant route. The final balloon normally has to be paid, refinanced or cleared through selling the car.
Does BAC offer PCP?
A current manufacturer-backed BAC PCP campaign could not be verified. An independent provider may offer PCP in some circumstances, but buyers should check the future-value and return terms rather than assuming it is available.
Can I use a financed BAC Mono on track?
Possibly, but the finance agreement and insurance policy need to allow the intended use. Ask both providers before taking the vehicle onto a circuit.
Can a company arrange BAC car finance?
Potentially. Company funding is possible in principle, but approval and tax treatment depend on the business, agreement and private use. Qualified tax advice is sensible before proceeding.
